We Specialise in Protecting You, Your Home & Your Loved Ones

Here at A₂B Financial, we strive to give our clients the best possible services. Moreover, we only offer guidance and a range of figures that meet your lifestyle. Our protection service is non-obligatory, and we do not charge any fees. Therefore, it is worth checking if A₂B Financial is the protection broker that you need.
Sadly, many people are often miss-sold insurance policies. Alternatively, it could be that people have an incorrect policy to meet their current needs. For a better understanding, please see the example below.
“You took out a standard life insurance policy, but since then you have had children.
Generally it’s worth updating your policy as your family grows. This will ensure you have the sufficient level of cover in place, if something was to happen to you unexpectedly.
If I’m married, do I have to have a joint cover?
The quick answer is “no.” However, if you are married and you have a joint mortgage, then we would advise getting a joint Mortgage Protection (Decreasing Term Assurance) policy. Why? We;l, we recommend this because most insurance companies require that the policy documents mirror your mortgage statement. Also, if you’re planning to start a family it is worthwhile taking out mortgage protection when you purchase or re-mortgage the property. This protection means that if something should happen to one of you, it will pay off the mortgage balance. Hence the technical term for this type of insurance: Decreasing Term Assurance, aka DTA.
The Different Types of Insurance
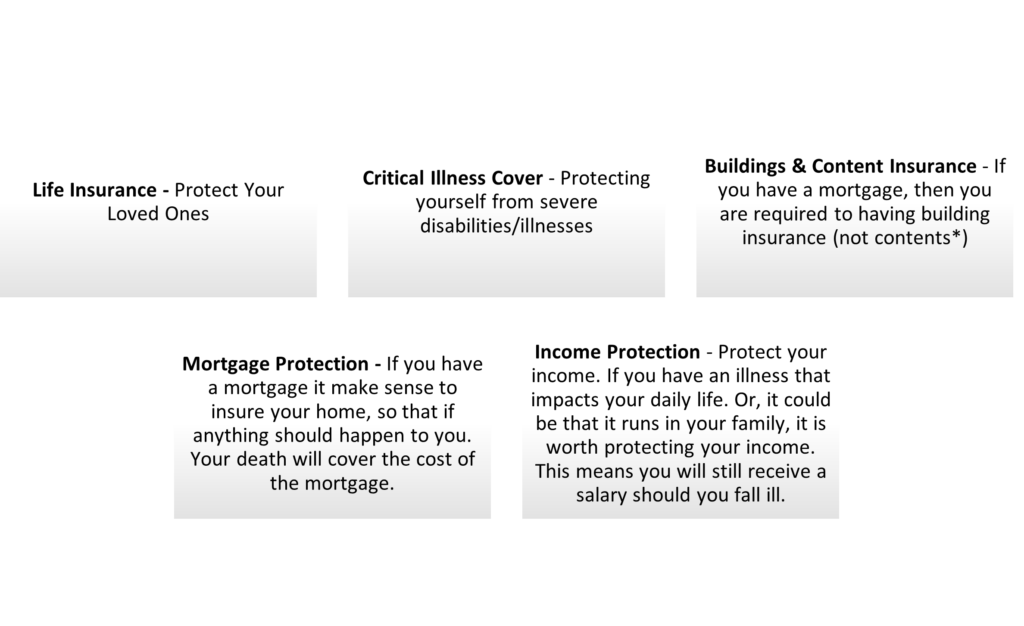
You Have a Single Mortgage Protection Policy, but you have got married.
Whenever your marital status changes, we recommend updating your policy documents. for example, if you have not updated your sername, the insurer may not pay out.
Why is it Important to Have Life Insurance?
Undoubtedly, life insurance is categorised as a luxury product. However, at A₂B Financial we believe that life insurance, especially self-protection and Critical Illness Cover (CIC). We would recommend that all parents take out CIC, because it means that if you were to get a critical illness, i.e., cancer, or you might have a stroke. Notably, you will receive your CIC pay out even if you survive.
It is worth noting that we think that every person should get life insurance. Why? Well, it simply because it means that your loved ones are taken care of should something happen to you unexpectedly. To refer to CIC again, this would mean that you can take time off work without worrying about your bills. Generally, CIC payments range from £10,000-£70,000. However, it is worth mentioning that CIC policies have higher premiums, as it’s more likely to pay out.
The Top Three Reasons Our Clients Take Out Adequate Protection
Unfortunately, when disaster strikes our world can sometimes be turned upside down. What happens if you are hit by a bus tomorrow? Who is going to look after your family? Pay for your home? Well, this is where life insurance comes in, as it helps you to protect those who you value the most. We believe that the top three reasons that clients take our protection because they want to:
- Protect your home
- Protect your family (children, partner, even parents)
- Protect yourself (you can have a CIC payout when you’re alive, as long as you keep up your monthly payments).
Surprisingly, life insurance is not as expensive as you might think. For instance:
You are a healthy, non-smoker, with no existing health problems. You want mortgage protection and CIC.
Average premiums: £10-£15. If you are a smoker, your premium will increase by 1.75%. Non-Smoker – £10.00 & Smoker – £17.50.